

Still Feel Behind in Retirement Savings? Why 2026 Is the Year to Take Action
By Dan Gould | Independent, Fee-only Fiduciary
Still feel behind in your retirement savings? You’re not alone—and you’re not out of time. A couple of years ago, we introduced three innovative strategies to help late savers take control of their future (see: Feel Behind in Your Retirement Savings? 3 Steps To Take Now). With market conditions shifting and interest rates steady, 2026 may be your most critical window yet.
At Three Streams Financial, we’ve helped countless families and professionals use these exact strategies to build resilience, boost income, and confidently retire.
This post will discuss:
- Why managing drawdowns is rule #1 if you feel behind
- How dividend income offers smarter, inflation-adjusted cash flow
- New 2026 updates to catch-up contributions and withdrawal strategies
Are you behind—or just waiting to catch your stride?
What Is Feeling Behind in Retirement Savings—and Why It Matters
Many investors believe they’ve missed the boat. But the real risk isn’t being behind—it’s failing to act. Inaction can be more damaging than any late start, especially in today’s high-valuation market environment.
Why 2026 Presents a Unique Opportunity for Retirement Planning
1. Avoiding Drawdowns Is Rule #1
Markets remain near record highs—but risks persist. The Shiller CAPE ratio continues to flash warning signs, and global uncertainty hasn’t disappeared. For those nearing retirement, now is the time to protect what you’ve built.
Sequence-of-returns risk is real.
Losses early in retirement can cause irreversible damage. That’s why smart investors focus on limiting drawdowns rather than chasing returns.
Smart moves for 2026:
- Use buffer ETFs to stay invested while minimizing downside.
- Incorporate risk overlays like trend-following and volatility targeting.
- Build multiple income sources so you’re never forced to sell low.
Focusing on “losing less” beats picking winners when time is short.
2. Focus on Dividend Cash Flow—Not Just Growth
Dividend Growth Investing is more than a strategy—it’s a mindset. And in 2026, it’s essential.
Why it works:
- Sticky inflation demands rising income, not just fixed yields.
- Dividend Aristocrats have consistently raised payouts—even in volatile years.
- Qualified dividends provide tax-efficient cash flow for retirees.
A $500,000 investment in a diversified dividend growth portfolio could double your annual income over 20 years, assuming 6–7% dividend growth and reinvestment.
PepsiCo—recently added to client portfolios—is a textbook example of what we look for. PepsiCo is now a Dividend King with 54 consecutive years of dividend increases, one of the longest unbroken growth streaks in the entire market. The stock currently pays an annualized dividend of roughly $5.92 per share, for a yield near 4%—well above its 5-year average yield of about 3%, reflecting recent price softness rather than any slowdown in the payout itself. That combination—a rising current yield plus a 54-year record of raises—is exactly the kind of consistency retirement plans need: income today, and a demonstrated habit of growing it every single year regardless of the economic backdrop.

Chart Source: FastGraphs.com
Want the full breakdown of why we added PepsiCo to client portfolios—including valuation, payout coverage, and how it fits into a broader dividend growth allocation? Read our deep dive: Dividend Growth Investing: Why PepsiCo Was Added to Client Portfolios.
3. Catch-Up Contributions + Smarter Withdrawals
For savers age 50+, 2026 brings new tools for building back faster.
Key updates for 2026:
- 401(k) catch-up limits have been raised.
- Secure 2.0 legislation allows Roth catch-up options in employer plans.
- Delaying Social Security now pays more—8% annual increase + inflation adjustments.
Pair those changes with a flexible withdrawal strategy—cutting back during downturns and drawing more during bull runs—and you can significantly extend your portfolio’s lifespan. In fact, a growing dividend stream can do a lot of that work for you automatically: see How Growing Dividends Can Raise Your Safe Withdrawal Rate in Retirement for the math behind it.
What the Trends Say
Dividend Income Growth Over Time
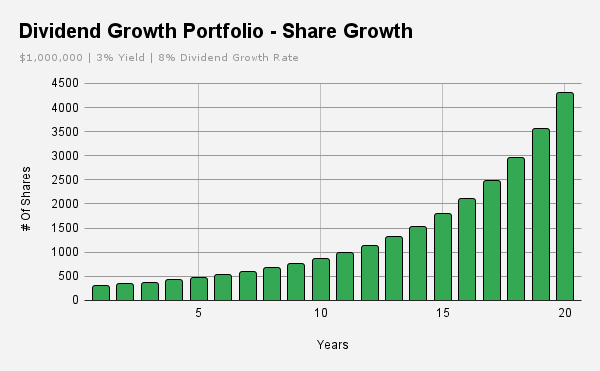
This visual illustrates why 2026 is a critical year to take action: Delayed action shrinks compounding power. Starting now maximizes future income.
In Conclusion
You’re not behind—you’re just getting started.
The opportunity to catch up is real—but only if you act. At Three Streams Financial, we help clients minimize drawdowns, build tax-efficient income, and confidently retire—even if they’ve felt behind for years.
You don’t have to be perfect. You need a plan that works.
Three Streams Financial is an independent, fee-only investment advisor that confidently helps working families and professionals retire. Contact us if you’re looking for tailored insights and a clear dividend income strategy.
Keep Reading
If dividend growth investing and catching up on retirement income are on your mind, these related posts dig deeper:
- Dividend Growth Investing: Why PepsiCo Was Added to Client Portfolios
- Why Now Is a Good Time to Look at Dividend Aristocrats
- Dividend Growth Investing at Record Valuations: What the 2008 Aristocrats Drawdown Teaches Us Now
- How Growing Dividends Can Raise Your Safe Withdrawal Rate in Retirement
- Case Study: A $150,000-a-Year Retirement Income Plan by 62
Key Takeaways
- Sequence-of-returns risk remains a top threat—mitigate it through diversification and drawdown control.
- Dividend growth investing offers rising, inflation-adjusted income—PepsiCo alone now yields near 4% with a 54-year streak of annual raises.
- 2026 updates to catch-up limits and Social Security make this a pivotal year.
- Consult a fee-only fiduciary financial advisor before making investment decisions.
Fee-Only Advice. Proven Process. Transparent Planning.
Remember, there’s no one-size-fits-all approach to investing. Do thorough research, consider your personal circumstances, and consult a fee-only financial advisor before making investment decisions.
Related Reading
For a step-by-step approach if you’re feeling behind, see 3 Steps to Take Now, or read how one mid-40s couple built a plan in our $150,000-a-Year Retirement Income Case Study. Learn more about our retirement income planning process, or reach out to get started.
Hello, I’m Dan Gould, an independent fee-only advisor based in Overland Park, KS. I offer comprehensive financial services to individuals, families, professionals, and small business owners nationwide. With over 25 years of experience in institutional financial markets, I deliver proven portfolio management and retirement income strategies.