

Shiller CAPE Ratio in 2026: What the 40+ Reading Means for Your Retirement
(Updated for 2026)
By Dan Gould | Three Streams Financial
Independent, Fee-Only Fiduciary Advisor
I recall sitting at my trading desk during the dot-com bubble, when the Shiller CAPE ratio reached 44. Everyone thought valuations no longer mattered. They were wrong. Today, with the ratio again sitting above 40, families need to understand what this signal means for their retirement savings.
Quick answer: The Shiller CAPE ratio (Cyclically Adjusted Price-to-Earnings ratio) measures how expensive the stock market is by comparing today’s S&P 500 price to the average of the past 10 years of inflation-adjusted earnings. The current Shiller CAPE ratio, as of 2026, sits at approximately 41 — more than double its long-run historical average of about 17, and close to the all-time record of 44.2 set during the 1999–2000 dot-com bubble.
The problem is that most investors are unaware of what the Shiller CAPE ratio measures or why it matters. They hear “the market is expensive” but don’t grasp the real-world implications. Since I started my career in the mid-1990s, I’ve seen firsthand how ignoring valuation metrics can devastate retirement plans.
This post will discuss:
- What the Shiller CAPE ratio tells us about market risk
- Why today’s 40+ reading creates specific challenges for retirees
- How to protect your portfolio when valuations flash warning signs
Are you still investing like valuations don’t matter?
What Is the Shiller CAPE Ratio—and Why It Works in 2026
The Shiller CAPE (Cyclically Adjusted Price-to-Earnings) ratio, developed by Nobel laureate Robert Shiller, measures the relative valuation of the stock market relative to earnings. However, what makes it different from regular P/E ratios is that it uses 10 years of inflation-adjusted earnings to smooth out business cycles.
Think of it this way. A regular P/E ratio is like checking today’s temperature to predict next month’s weather. The Shiller CAPE ratio examines the past decade of seasons to provide a clearer picture. It filters out the noise of temporary earnings spikes or crashes.
My trading floor experience taught me that markets can stay irrational longer than you think. But the CAPE ratio has proven remarkably consistent at identifying when investors are paying too much for future earnings. When it’s high, future returns tend to be low. When it’s low, future returns tend to be strong.
The formula is straightforward: current S&P 500 price divided by the 10-year average of inflation-adjusted earnings. The historical average sits around 17. Today’s reading near 41 means investors are paying roughly double the historical norm for each dollar of earnings — and the S&P 500’s dividend yield has fallen to around 1.1%, near the low end of its range over the past century.
Why the Shiller CAPE Ratio Above 40 Matters More Than Ever
The current Shiller CAPE ratio, at approximately 41, places us in rare territory — closing in on the all-time record of 44.2 set at the peak of the dot-com bubble. We’ve only seen levels this high a handful of times in market history: 1929, before the Great Depression; 1999–2000, during the dot-com bubble; and 2021, during the pandemic stimulus surge.
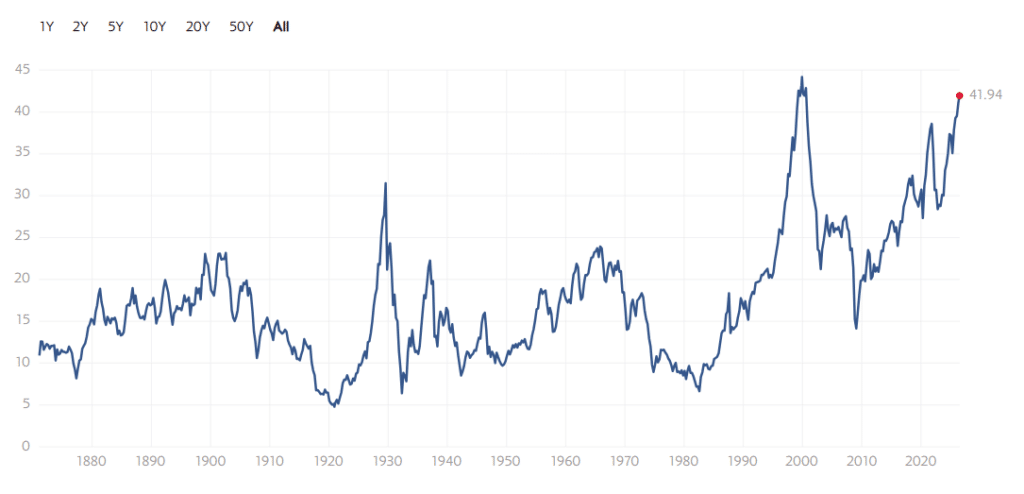
What happened after those peaks? The 1929 crash led to an 89% decline in the stock market. The dot-com crash saw the S&P 500 fall 49% and the NASDAQ drop 78%. The 2022 correction was milder but still painful, with many growth stocks losing 50-80% of their value.
Here’s the critical point for families approaching retirement: high CAPE ratios don’t predict timing, but they strongly predict poor long-term returns. Research shows that when the CAPE exceeds 30, the S&P 500’s average 10-year forward return drops to just 3.4% annually. That’s before inflation.

For someone retiring with a million-dollar portfolio, the difference between the historical average return (10%) and the high-CAPE return (3.4%) is staggering. Over 20 years, that gap could mean the difference between $6.7 million and $1.9 million. That’s why valuation matters.
What the Data Shows: Forward Returns at High CAPE Levels
Historical data reveal a clear pattern when the Shiller CAPE ratio reaches extreme levels. Since 1881, whenever the ratio exceeded 30, the returns of the following decade averaged less than 4% annually. But the real risk isn’t just low returns—it’s the drawdowns.
Markets with CAPE ratios above 30 experienced average maximum drawdowns of 35% over the next decade. For retirees withdrawing 4% annually, a 35% drop combined with ongoing withdrawals can create an unrecoverable spiral. I’ve watched families cut their retirement spending in half after experiencing poorly timed market crashes. This is part of why we’ve written about why the traditional 60/40 portfolio still fails in 2026 — a static stock/bond split doesn’t adjust for valuation risk the way a quality-focused, income-generating strategy can.

The data also shows something else: expensive markets can get more expensive before they correct. In 1997, the CAPE hit 30, and many advisors recommended selling everything. The market then gained another 80% before crashing. Timing markets based solely on valuation is a fool’s game.
What works is adjusting your risk exposure and expectations. When I managed institutional money, high valuation readings meant we’d reduce risk allocations, increase quality standards, and build larger cash reserves. The same principles apply to family portfolios. It’s also why we lean so heavily on Dividend Aristocrats and other quality dividend growers — companies like PepsiCo, which have a decades-long record of raising payouts through every kind of market, expensive or not. This is the same philosophy behind our Dividend Growth Investing approach for 2026.
What to Do When the Shiller CAPE Ratio Signals Risk
Working with families has shown me that successful investing during high-valuation periods requires three adjustments. First, shift your portfolio toward high-quality dividend-growth stocks with reasonable valuations. Even in expensive markets, some sectors trade at fair prices — see our related post on what the 2008 Dividend Aristocrats drawdown teaches us about investing at today’s record valuations.
Second, build what I call a “buffer fund”—a cash reserve equal to 2-3 years of living expenses. This prevents forced selling during the inevitable correction. One could also utilize buffer ETFs to maintain equity exposure while limiting downside risk.
Third, consider tax-efficient strategies to reduce equity exposure. If you have significant gains, strategic tax-loss harvesting or charitable giving can help reduce your tax liability without incurring massive tax bills. The goal isn’t market timing—it’s risk management.
Most importantly, don’t abandon your investment plan. Markets can remain expensive for years. But do adjust your withdrawal assumptions. If you’re planning for 4% withdrawals with a CAPE above 40, consider a less rigid, more flexible spending strategy instead — a rising dividend stream can help; see How Growing Dividends Can Raise Your Safe Withdrawal Rate in Retirement. Minor adjustments today prevent painful cuts tomorrow.
In Conclusion: The Shiller CAPE Ratio and Your Financial Future
The Shiller CAPE ratio above 40 sends a clear warning about market risk and future returns. While it can’t predict when a correction will occur, it strongly suggests that the returns of the next decade will likely disappoint investors expecting historical averages.
At Three Streams Financial, we help families navigate high-valuation markets with strategies designed to protect capital while maintaining growth potential. Our dividend growth investment management approach specifically targets companies trading at or below their historical valuations, even in expensive markets.
You don’t have to predict the market’s next move. You need a plan that acknowledges current risks and positions your portfolio accordingly. The families who thrive through market cycles are those who respect valuation signals and adjust before a crisis hits. If you feel like you’re behind on retirement savings, high valuations don’t have to derail your plan — see Still Feel Behind in Retirement Savings? Why 2026 Is the Year to Take Action.
Understanding metrics like the Shiller CAPE ratio enables you to make informed decisions rather than relying on hope. Hope isn’t a strategy—preparation is.
Key Takeaways
- The Shiller CAPE ratio is near 41 in 2026 — approaching the all-time record of 44.2 set during the dot-com bubble — and historically signals below-average returns and higher risk over the next decade
- High valuations don’t predict timing but strongly predict poor 10-year forward returns, averaging just 3.4% annually when CAPE exceeds 30
- Successful navigation requires quality focus, buffer funds, and adjusted withdrawal rates—not market timing
- You don’t have to be perfect. You need a plan that works.
Fee-Only Advice. Proven Process. Transparent Planning.
Remember, there’s no one-size-fits-all approach to investing. Conduct thorough research, consider your personal circumstances, and consult a fee-only financial advisor before making any investment decisions.
P.S. Want to see exactly where you stand? I’ve created a free Personalized Retirement Map that addresses all four critical areas: Income, Investments, Planning, and Legacy. No pitch, just clarity.

Hello, I’m Dan Gould, an independent fee-only advisor based in Overland Park, KS. I offer comprehensive financial services to individuals, families, professionals, and small business owners nationwide. With over 25 years of experience in institutional financial markets, I deliver proven portfolio management and retirement income strategies.