
Get Your Free Personalized Retirement Map
A Real-World Planning Framework for Overland Park & Kansas City Families
Independent, fee-only fiduciary advice. Your assets are always held independently at Charles Schwab — I never take custody of your money.
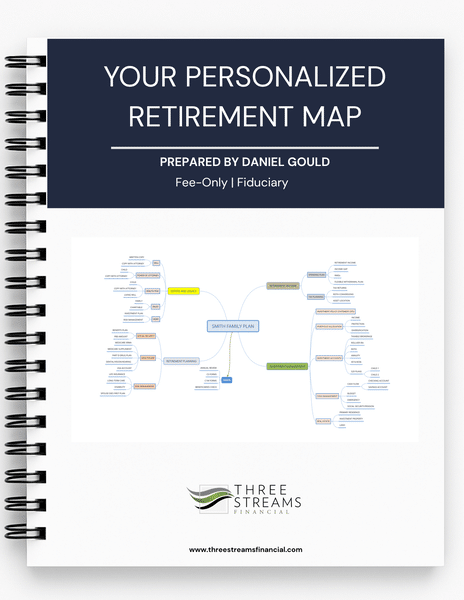
One Map. Four Pillars. A Plan That Actually Fits Your Life.
After 25+ years in the financial industry, I've learned that most families think retirement planning means picking the right mutual fund. It doesn't. Real financial security comes from four pillars working together — and your free Personalized Retirement Map shows you exactly how they fit for your specific situation.
Retirement Income — Making your money last when the paychecks stop.
Investment Management — Portfolios built with a purpose, not a sales pitch.
Retirement Transition Planning — Social Security, Medicare, and healthcare, handled before open-enrollment panic sets in.
Estate & Legacy — Getting your documents and beneficiaries in order so your family isn't left guessing.
Part 1: Retirement Income That Grows, Not Shrinks
Goal: Create multiple income streams that grow over time, not shrink with inflation.
Retirement becomes all about income once the paychecks stop. I've managed institutional portfolios, but helping a retired couple figure out how to pay their bills from savings is a different kind of math — and it matters more.
Our income strategy:
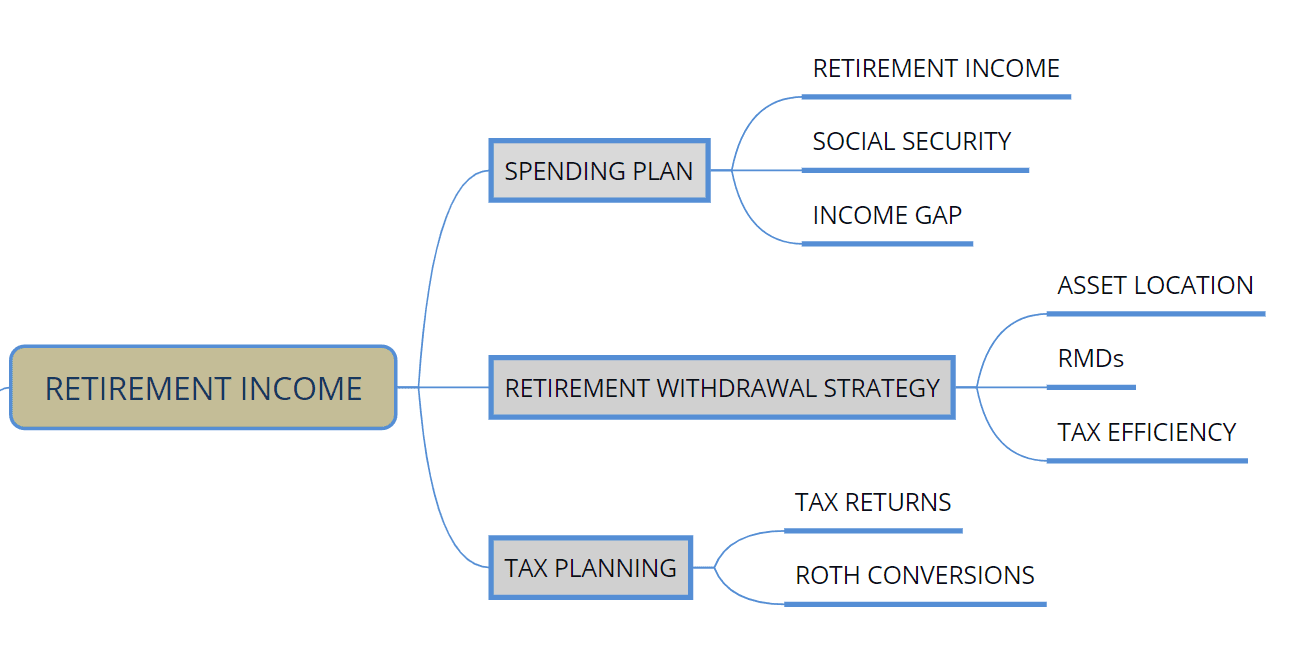
- Starts with your spending plan — we define annual cash flow targets (checking, savings, emergency reserves) so we know exactly how much income you need each year.
- Identifies your income gap between guaranteed sources (Social Security, pensions) and estimated expenses. Any shortfall is covered by smart portfolio withdrawals.
- Uses withdrawal sequencing and tax strategies — which accounts to tap first, and how much to withdraw safely once RMDs kick in. We plan these moves years in advance.
- Builds income you can count on through dividend growth investing, because rising dividends help keep up with inflation.
- Plans for inflation protection with strategies that have historically outpaced rising costs — not the latest investment fad.
Every portfolio gets a written Investment Policy Statement, because when markets get scary — and they will — you need to remember why you made the decisions you made.
Part 2: Investment Management Without the Sales Pitch
Goal: Create a diversified portfolio that provides both protection and growth. I don't sell products — never have, never will.
Our investment approach:
- Customized to your situation — your Investment Policy Statement reflects your goals, timeline, and real risk tolerance.
- Portfolio allocation with a purpose — every account (taxable brokerage, Roth IRA, 401(k)/403(b), 529) is positioned for your income needs and tax situation.
- Protection through diversification across strategies including dividend growth investing, bonds, and buffer funds — diversification means owning things that respond differently to market conditions, not just owning more things.
- Asset location strategy — taxable for flexibility, tax-deferred for growth, Roth for tax-free income, each serving your withdrawal sequence.
- Focus on what you can control — costs, tax efficiency, and allocation, since we can't control returns.
I've experienced multiple market crashes, bubbles, and "once-in-a-lifetime" events. The families that did best weren't chasing performance — they had a plan and stuck to it.

Part 3: A Retirement Transition Plan That Actually Works
Goal: Optimize every part of your retirement transition and ongoing management.
Our retirement strategy:
- Social Security optimization — we calculate your Full Retirement Benefit first, then determine optimal claiming timing. This can mean tens of thousands of dollars over your lifetime.
- Medicare maze navigation — Parts A, B, C, and D, plus IRMAA thresholds and drug plans, handled before open-enrollment panic sets in.
- Healthcare cost reality — HSAs offer triple tax advantages if you're eligible, but most people use them wrong. We also evaluate long-term care options before you need them.
- Risk management that makes sense — life insurance, long-term care, and disability coverage as tools to protect your plan, not products to sell.
This isn't about following someone else's retirement template. It's about building a plan that fits your life and your family's needs.

Part 4: Estate & Legacy Planning That Prevents the Preventable
Goal: Protect your assets and make sure your wishes are carried out efficiently.
Estate planning isn't about how much money you have — it's about avoiding the situations I've watched families go through when someone gets sick or passes away without a clear plan. Adult children who can't access accounts. Spouses who discover beneficiaries were never updated after a divorce. Families in court because documents don't match. These aren't "wealthy people's problems" — they happen to working families every day.
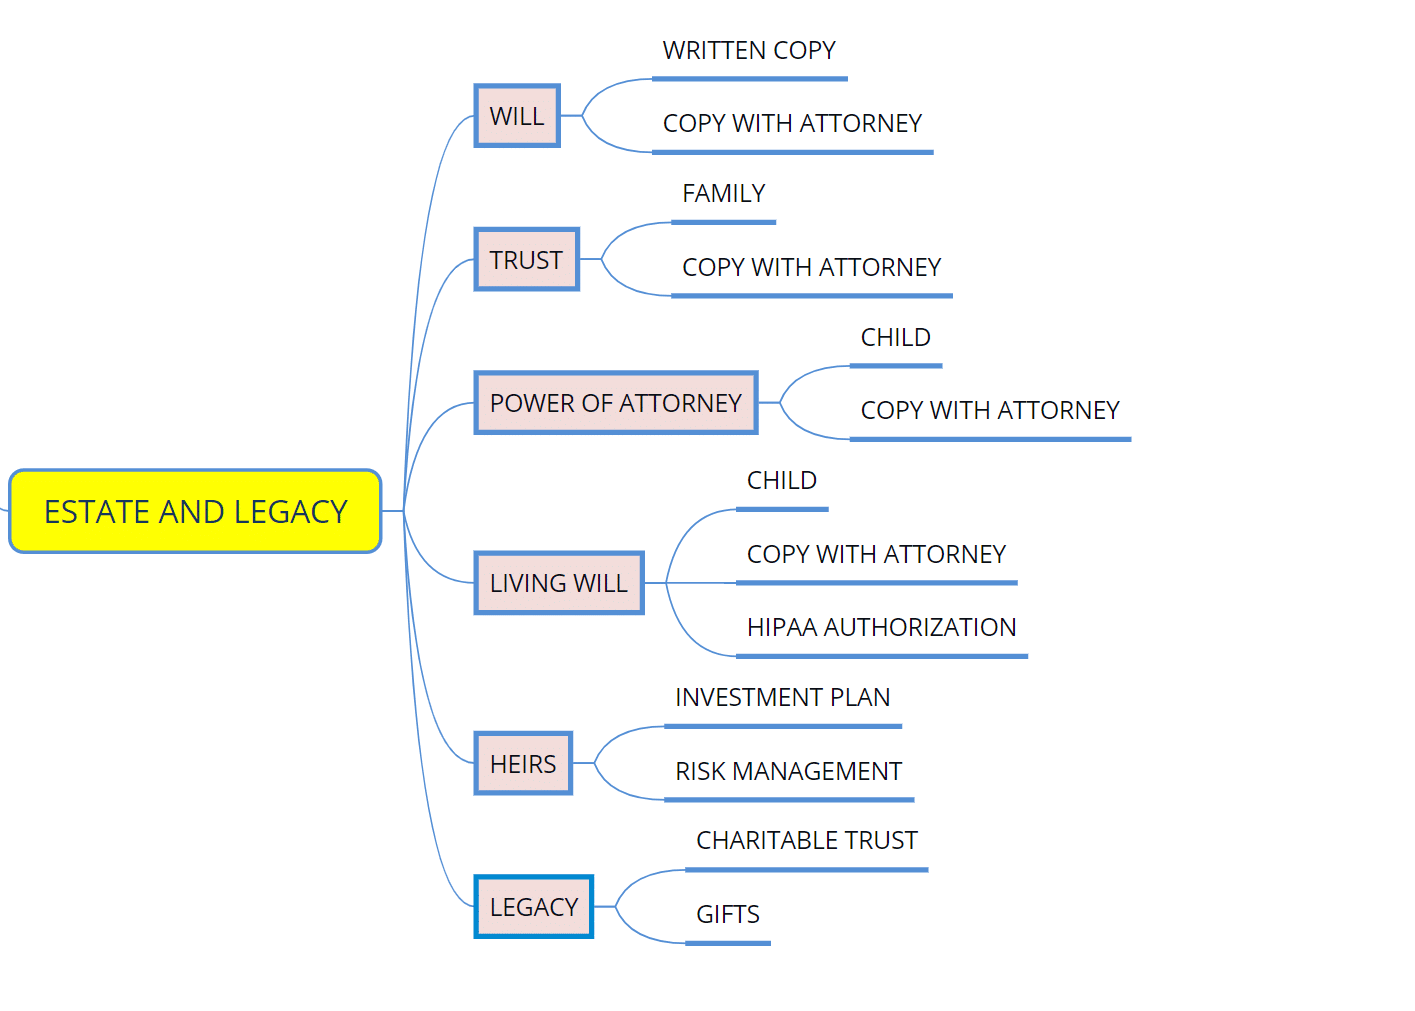
- Coordinating your accounts with your intentions — investment accounts need to match your will and trusts. You'd be surprised how often they don't.
- Annual beneficiary checkups — outdated designations cause more problems than market crashes.
- Essential documents in order — wills, POAs, and healthcare directives, kept current and accessible to the people who need them.
- Trust strategies when appropriate — revocable living trusts, charitable trusts, and special needs trusts, evaluated for your specific goals.
- Working with your estate attorney — see our full Estate & Legacy Planning service page for more detail.
The goal isn't perfection — it's preventing the preventable problems that make difficult times even harder for the people you care about.
Keeping Your Plan on Track: Annual Reviews & Ongoing Coordination
Having a plan is one thing. Keeping it on track is another. Ongoing management includes:
- Annual plan reviews — we meet every year to make sure your plan still fits your life, since goals, laws, and families change.
- Secure document storage — wills, trusts, beneficiary forms, and investment policies stored securely with version control, so nothing gets lost in a file cabinet during an emergency.
- Coordination with tax, legal, and insurance professionals — your financial strategy should support your tax planning and estate design, not work against them.
- Straight guidance, no agenda — every recommendation is in your best interest, because that's my legal obligation as a fiduciary.
The families that succeed long-term aren't necessarily the ones who start with the most money — they're the ones who get organized, make good decisions consistently, and adjust when life throws curveballs.