
Replace Stock Market Uncertainty with Predictable, Growing Cash Flow.
Independent, fee-only fiduciary wealth management for Kansas City pre-retirees and business owners. We build customized dividend growth portfolios designed to replace your current paycheck with a reliable, lifetime retirement salary.
Who does Three Streams Financial serve in the Kansas City metro area?
- All client assets are safely and independently housed by Charles Schwab
- Custom planning for wealth accumulators ($300k+) and pre-retirees ($500k+).
- I am a fiduciary under the Investment Advisers Act of 1940.
- Transfer wealth efficiently and reduce taxes with flexible planning.
- Maximize Social Security and Medicare benefits.
What We Do: Investment Management, Retirement Planning, Estate & Legacy, Medicare Planning
Investment and Portfolio Strategy
-
Tailored portfolio design and investment advice
-
Comprehensive management focused on maximizing your financial securit
Retirement And Social Security Planning
-
Build reliable retirement income with smart Social Security timing and inflation protection
-
Secure a prosperous financial future
Taxes and Estate Needs Planning
-
Basic estate, inheritance, and legacy wealth management
-
Tax reduction strategies and required minimum distributions (RMDs)
Healthcare and Protection
-
Medicare, prescription drugs, and IRMAA avoidance
-
Long-term care, risk management, and insurance planning
What makes Three Streams Financial different from other wealth management firms? Trust And Transparency.
- Transparency: No hidden fees, no conflicts-just honest advice you can trust.
- Comprehensive Management: All your accounts in one place-easy access to your finances, anytime, anywhere.
- Security: Your assets and privacy are protected by top-tier custodian Charles Schwab-safety is paramount.
- Experience: 25+ years in finance-offering real advice and active risk management, always in your best interest.
- Personalization: Independent advice tailored to your unique life-I've faced your challenges and am here to help.
| Advisory Service Pillar | Three Streams Financial Structure | Traditional Commission Broker |
|---|---|---|
| Fiduciary Status | Yes (100% Fee-Only) | No (Held to standard suitability rules) |
| Hidden Asset Fees | $0 (Zero wrap-fee markups) | Common (Hidden mutual fund 12b-1 fees) |
| Annual Advisory Fee | 0.50% - 0.95% of assets | Often 1.00% - 1.50%+ plus trade tickets |
| Product Incentives | None (No annuity commissions) | High incentives to push internal funds |
Table 1.1: A transparent breakdown of the 100% fee-only fiduciary pricing structure at Three Streams Financial compared to traditional commission-based broker models in Overland Park, KS.
What is the investment philosophy at Three Streams Financial?
Three Streams Financial is a 100% fee-only fiduciary that builds high-quality dividend growth portfolios designed to replace market uncertainty with predictable, growing cash flow. We don't rely on market timing or speculative bets. Our philosophy is simple: own durable, well-capitalized companies that consistently raise their dividends, hold them long-term, and let compounding turn steady income into lasting wealth — especially through the volatile years leading into and through retirement.
Why dividend growth? It turns market volatility into growing cash flow.
Dividend growth creates a rising income stream you can live on today, so you don't have to sell shares at the worst time.
Companies that raise dividends year after year signal durable earnings and disciplined management. That growing income keeps pace with inflation, funds your living expenses, and means you can hold through downturns instead of being forced to sell into them.
How we protect retirement portfolios against downside market risk.
We diversify across sectors, hold cash reserves, and favor defensive, high-quality dividend payers to soften drawdowns.
No strategy avoids every downturn, but a portfolio built on resilient balance sheets and steady cash flow historically recovers faster. Our goal is to keep your retirement plan on track through the inevitable corrections — so market swings don't force permanent changes to your lifestyle.
| Retirement Protection Goal | Traditional 60/40 Portfolio Target | Three Streams Multi-Strategy Framework |
|---|---|---|
| Inflation Protection | Fixed-income coupon yields lose real buying power over long horizons | Dividend Growth Stocks actively increasing baseline cash payouts |
| Downside Risk Mitigation | Relies entirely on broad historical bonds holding up during crisis parameters | Dedicated Buffer Funds engineered to cap structural equity drawdowns |
| True Correlation Drag | High correlation spike when stock & bond indexes crash together simultaneously | Independent Alternative Income allocations lowering net portfolio variance |
Table 1.2: Comparison of real retirement risk mitigation outcomes, illustrating how a multi-strategy approach solves the structural inflation and correlation failures of a standard 60/40 index portfolio.
Frequently Asked Questions
 Free Workshop: Dividend Growth Investing — Overland Park
Recent Insights
A few honest, opinionated takes — not the generic advice you'll find everywhere else.
-
Still Feel Behind in Retirement Savings? Why 2026 Is the Year to Take Action
By Dan Gould | Independent, Fee-only Fiduciary Still feel behind in your retirement savings? You’re not alone—and you’re not out of time. A couple of years ago, we introduced three innovative strategies to help late savers take control of their future (see: Feel Behind in Your Retirement Savings? 3 Steps To Take Now). With market…
-
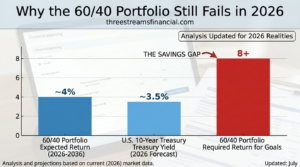
Why the 60/40 Portfolio Still Fails in 2026
By Dan Gould | Independent, Fee-only Fiduciary Updated July 2026 to reflect current valuation and interest-rate data. Why the 60/40 portfolio fails is a critical issue for today’s investors. Once considered the gold standard for retirement planning, the 60/40 model struggles to keep pace with inflation, market volatility, and stretched valuations — and the last…
-
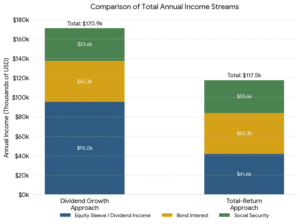
Case Study: A $170,900-a-Year Retirement Plan — What Happens If the Market Underperforms for 15 Years
By Dan Gould | Three Streams Financial — Independent, Fee-Only Fiduciary Advisor Client profile: Doug, 50, a business owner comfortable with a 60% equity / 40% bond risk profile. Names and identifying details have been changed for privacy — see compliance note at the end. A worry we hear from clients in their 50s: “What…
-
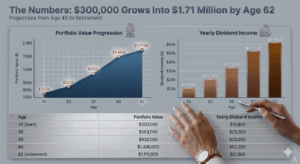
Case Study: A $150,000-a-Year Retirement Income Plan by 62
By Dan Gould | Three Streams Financial — Independent, Fee-Only Fiduciary Advisor Client profile: Mark and Julie, mid-40s, with a small inheritance. Names and identifying details have been changed for privacy — see compliance note at the end. Every year, we meet couples in their mid-40s who feel behind on their retirement savings. They’re doing…
Founder | Portfolio Manager
Daniel Gould
I am an independent investment adviser representative (IAR) based in Overland Park, KS, serving individuals, families, professionals, and small business owners nationwide. With over 25 years of experience in the financial markets, I apply institutional-grade trading and portfolio management strategies to help clients achieve their financial goals.
I am a fiduciary under the Investment Advisers Act of 1940. This means I am held to a strict fiduciary duty, which has two components: a duty of care and a duty of loyalty.
- The duty of care requires me to provide impartial and objective advice in my client's best interests, based on their specific circumstances and investment objectives.
- The duty of loyalty component requires me not to place my interests ahead of my clients and to provide complete and fair disclosure of all material facts related to the advisory relationship, including fees and conflicts of interest.
Our Local Service Areas:

Ready To Take Control Of Your Financial Prosperity?
No pressure. No sales pitch. Just a transparent conversation.