

The Power of Dividend Growth Investing: How Compounding Builds Financial Freedom
By Dan Gould | Three Streams Financial — Independent, Fee-Only Fiduciary Advisor
Most people understand dividends. Far fewer understand compounding dividend growth — and that gap is exactly where the real wealth-building happens. The longer dividend growth investing sits in a portfolio, the more it compounds, not just linearly but exponentially. This post breaks down the actual mechanics, with real numbers, so you can see why that distinction matters so much.
Quick answer: Dividend growth investing compounds in two layers at once — the dividend itself grows every year, and reinvested dividends buy more shares that generate even more dividends. A $10,000 investment with a 3% starting yield and 8% annual dividend growth, fully reinvested, could grow to over $35,000 in dividends alone over 20 years. On a $1,000,000 portfolio under the same assumptions, that can mean over $200,000 a year in dividend income without ever touching the original principal.
This post will cover:
- What dividend growth investing actually is, with a real 60-year example
- Why compounding dividend growth works differently — and more powerfully — than compounding a flat payout
- What this can look like on a real $1,000,000 portfolio over 20 years
What Is Dividend Growth Investing?
Dividend growth investing means holding shares of companies with a consistent, long-term record of paying — and raising — their dividend, then reinvesting those payouts back into more shares of the same or similar companies. It’s a narrower, more selective approach than simply buying whatever pays the highest current yield.
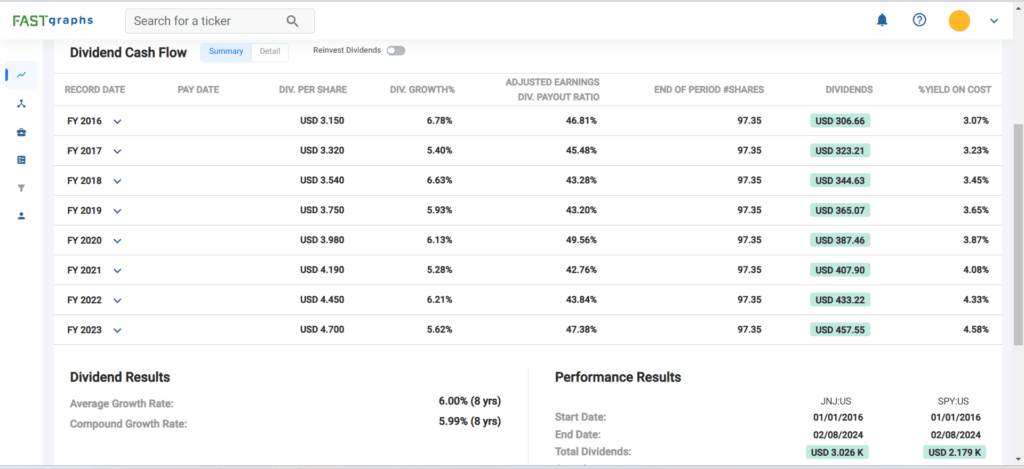
Here’s a real example. The table below, from Fastgraphs.com, shows the dividend history of Johnson & Johnson (JNJ). The dividend paid per share rose from $3.15 in 2016 to $4.70 in 2023 — a compound annual growth rate of roughly 6% over that stretch. What makes this genuinely remarkable isn’t the 2016-2023 window specifically — it’s that JNJ has raised its dividend every single year for over six decades, through recessions, oil shocks, the dot-com crash, 2008, and the pandemic. That kind of track record is the entire point of dividend growth investing: it’s a screen for financial discipline and durability, not just a current yield number.
Why Dividend Growth Compounds Differently Than a Flat Payout
Dividend growth investing combines three separate sources of growth, all compounding at the same time:
- Compounding dividends — reinvested payouts buy more shares, which generate their own dividends
- Compounding the growth of dividends per share — each of those shares is also getting a raise every year
- The increasing value of the shares themselves — as earnings and dividends grow, share prices have historically tended to follow
Here’s why that combination matters so much more than a fixed-income comparison. Imagine you earn a $1 dividend on a stock you own. Reinvest that dollar, and it earns its own return — you’re compounding on your original investment and on the accumulated dividends. Now add the fact that the dividend itself is also growing every year, and you get two compounding effects stacked on top of each other, which is exactly why the growth curve isn’t linear — it’s exponential.

Here’s the simple math behind that chart: invest $10,000 in a company with a 3% initial dividend yield. If the company raises its dividend by 8% a year and every dividend gets reinvested, that position could generate over $35,000 in cumulative dividends alone over 20 years — on top of whatever the shares themselves are worth by then. These are hypothetical assumptions used for illustration, not a guarantee of future returns, but they illustrate the mechanism clearly.
What This Looks Like on a $1,000,000 Portfolio
Take a couple in their 40s with a $1 million nest egg to invest. Assuming a 3% starting yield, 8% annual dividend growth, and 8% annual share price appreciation — hypothetical assumptions, not a projection or guarantee — reinvested dividend growth compounding for 20 years can produce a very different retirement picture than most people expect.
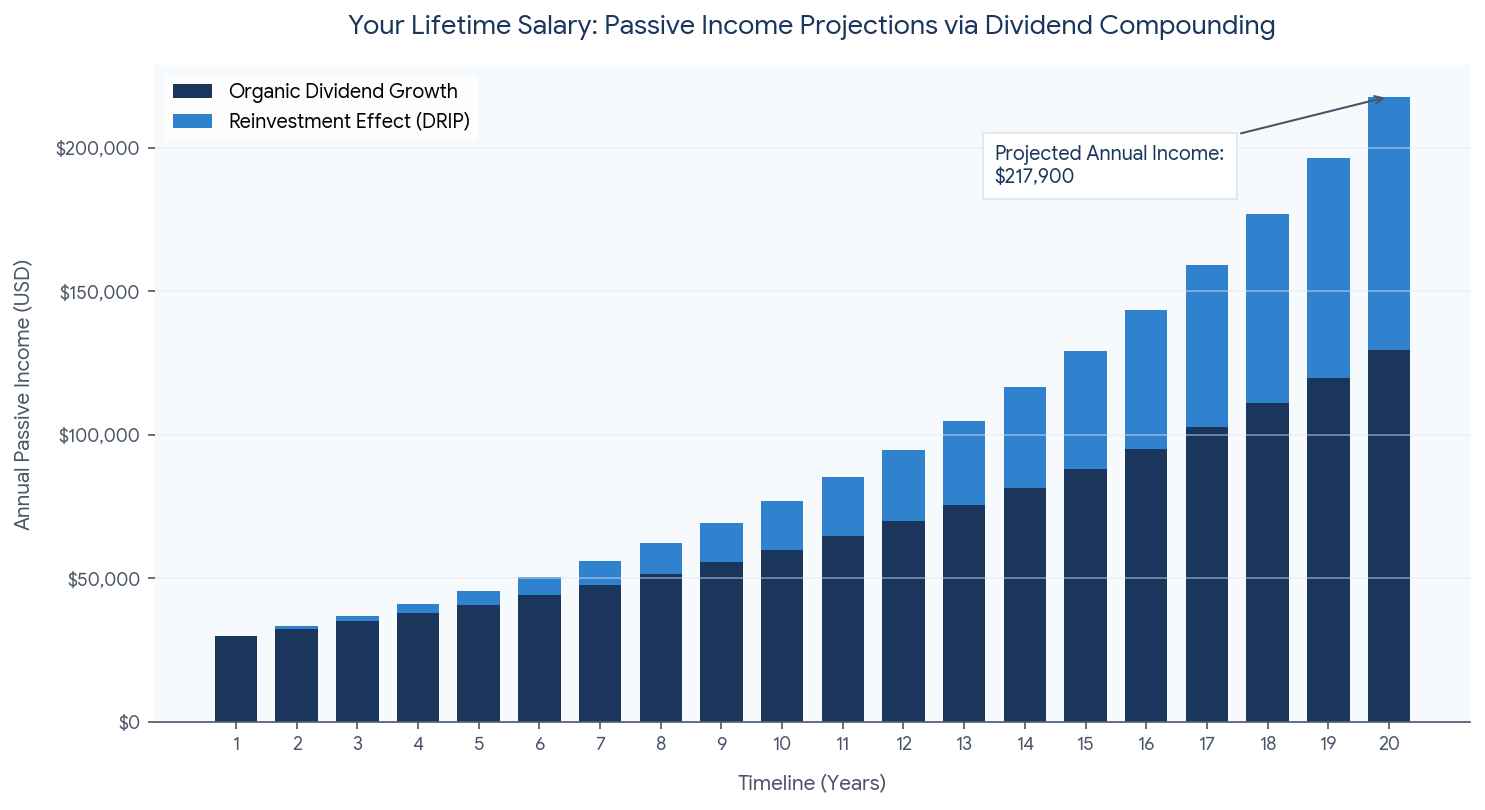
Under those assumptions, this couple could eventually generate more than $200,000 a year in dividend income without ever selling a share of principal. That’s the entire premise behind building a portfolio around dividend growth rather than pure price appreciation: the goal isn’t to time the market, it’s to own a rising income stream that keeps growing for as long as you need it to.
We help clients build exactly this kind of portfolio — whether you’d like to manage it yourself with our guidance, or have us manage it for you.
LEARN MORE AT OUR FREE DIVIDEND GROWTH WORKSHOP COMING UP SOON – CLICK HERE!
Frequently Asked Questions
How does dividend growth compounding actually work?
It works through two layers of compounding at once: reinvested dividends buy additional shares, and the dividend paid per share also grows every year. Together, this produces exponential rather than linear growth in your total dividend income over time.
How much can dividend reinvestment actually grow over 20 years?
Under hypothetical assumptions of a 3% starting yield and 8% annual dividend growth, a $10,000 investment with dividends fully reinvested could generate over $35,000 in cumulative dividends over 20 years. On a $1,000,000 portfolio under the same assumptions, that can translate to over $200,000 a year in dividend income without touching the original principal.
What makes a stock a “dividend growth” stock rather than just a dividend stock?
A dividend growth stock has a long, consistent track record of raising its dividend every year — sometimes for decades — rather than simply paying a high current yield. That track record tends to reflect a mature, stable, profitable business with strong cash flow, which is a very different quality signal than yield alone.
Key Takeaways
- Dividend growth investing focuses on companies with a long history of steadily raising their dividend, not just companies with a high current yield.
- These companies are typically mature, stable, and profitable, with strong, consistent cash flow.
- Reinvesting growing dividends compounds in two layers at once — more shares, and a growing payout per share — producing exponential rather than linear growth.
- On a large enough portfolio, this can eventually produce six figures in annual income without ever touching the original principal.
Fee-Only Advice. Proven Process. Transparent Planning.
Remember, there’s no one-size-fits-all approach to investing. Do your research, carefully consider your circumstances, and consult a fee-only fiduciary advisor before making investment decisions.
P.S. Curious what a dividend growth core would look like in your own portfolio? I’ve created a free Personalized Retirement Map that addresses all four critical areas: Income, Investments, Planning, and Legacy. No pitch, just clarity. → Get Your Free Personalized Retirement Map
Related Reading
For an updated, deeper look at this strategy, see Dividend Growth Investing in 2026, and read more on the tax side in The Magic of Dividend Growth Investing: How to Outpace Inflation in 2026. See how a rising dividend stream can support a higher retirement withdrawal rate in How Growing Dividends Can Raise Your Safe Withdrawal Rate in Retirement. Learn more about our investment management approach, or get in touch to talk through your own plan.
Hello, I’m Dan Gould, an independent fee-only advisor based in Overland Park, KS. I offer comprehensive financial services to individuals, families, professionals, and small business owners nationwide. With over 25 years of experience in institutional financial markets, I deliver proven portfolio management and retirement income strategies.