

What is a Fee-Only Fiduciary Financial Advisor? (And Why It Matters in Overland Park)
By Dan Gould | Three Streams Financial — Independent, Fee-Only Fiduciary Advisor
If you’re searching for a fee-only financial advisor in Overland Park, KS, you’ve probably run into two very different business models: fee-only and commission-based. This distinction determines whose interests your advisor must prioritize, directly affecting your retirement plan’s security.
Quick answer: A fee-only financial advisor is paid directly by clients — never by commissions, product sales, or referral fees — and is legally held to a fiduciary standard requiring them to act in your best interest at all times. A commission-based advisor is paid by the companies whose products they sell, and is typically held to a lower “suitability” standard, meaning a recommendation only needs to be suitable, not necessarily the best option available. You can verify any advisor’s fee-only, fiduciary status by searching their CRD number at the SEC’s Investment Adviser Public Disclosure website (adviserinfo.sec.gov).
Here’s a plain-English breakdown of the difference, and why it matters more than most people realize.
What Does “Commission” Financial Advisor Mean?
A commission-based advisor is paid by the companies whose products they sell — think mutual funds, variable annuities, or insurance policies. The more of a particular product they sell, the more they earn. Commission-based pay creates conflicts—what pays the advisor most may not be best for your retirement. Commission advisors are typically held to a “suitability” standard — meaning a product just has to be suitable, not necessarily the best option available to you.
What Is a Fee-Only Financial Advisor?
A fee-only advisor is paid directly by clients — not by product companies, fund families, or insurance carriers. There are no commissions and no sales quotas. You pay for advice, planning, and ongoing management, full stop.
This is the model we use at Three Streams Financial in Overland Park. As an Investment Adviser Representative (IAR) registered under the Investment Advisers Act of 1940, I’m held to a fiduciary standard — legally obligated to act in your best interest at all times, not just when it’s convenient. You can verify any advisor’s IAR registration yourself at the SEC’s Investment Adviser Public Disclosure website (adviserinfo.sec.gov).
No Sales Quotas, No Pressure to Sell — By Design
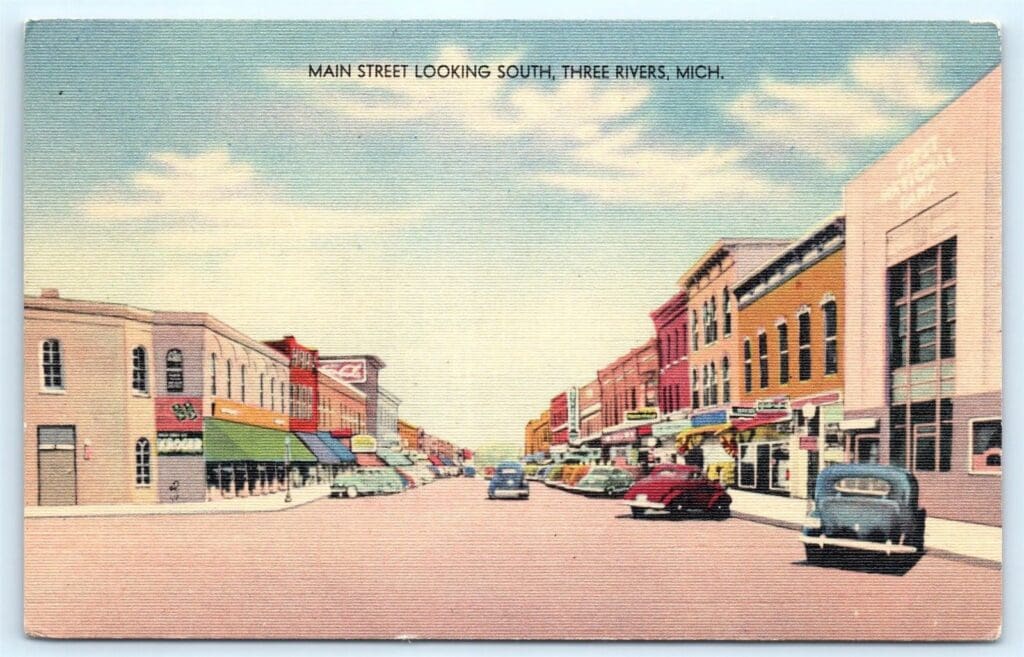
I grew up in Three Rivers, a small, blue-collar town in Michigan—a place where people worked hard. That experience taught me to deeply value every dollar. That’s a big part of why I chose the independent, fee-only path. Nobody is telling me what to push this quarter, and there’s no home-office sales target hanging over my recommendations. I get to choose the families I work with, and every recommendation is made because it’s right for you—not because it’s good for a company’s bottom line.
The Fiduciary Difference: Why “IAR” Actually Matters
“Fiduciary” is used loosely in marketing, so it’s worth being specific: A true fiduciary must prioritize your interests, disclose any conflicts, and recommend what’s best for your goals and risk tolerance. That’s a meaningfully higher bar than the suitability standard commission-based brokers operate under, and it’s the biggest reason people search for a fee-only advisor in the first place. If you’re vetting more than one advisor, see the specific questions worth asking before hiring anyone, since “fiduciary” alone doesn’t guarantee consistency across every recommendation.
Independent Doesn’t Mean Unprotected
One misconception is that “independent” advisors are somehow less secure than advisors at a big-name brokerage. In practice, it’s the opposite. Independent, fee-only advisors typically custody client assets with a third-party custodian rather than holding the funds themselves. We use Charles Schwab as a third-party custodian, so your assets are held safely in your name, not ours. You get personal attention and top-tier security from one of the nation’s largest custodians.
Access to Every Product, Not Just One Firm’s Menu
This is where the two models diverge, directly affecting your returns. A commission-based advisor is often limited to the products approved by their broker-dealer or insurance company — sometimes proprietary funds designed to generate revenue for the parent company. An independent, fee-only advisor has no such restriction. Because there’s no product company paying the bill, I can select from the entire universe of stocks, bonds, and ETFs across every firm in the market to build the portfolio that’s actually right for you.
You and I Decide Together How to Invest
Being product-agnostic also means the investing decisions stay collaborative. We build your portfolio together, based on your goals and risk tolerance; your involvement is always your choice. Some clients prefer to review and approve every move; others prefer we manage it day to day. Either way, it’s a conversation between us, not a pitch.
Real-Time Pricing vs. Once-a-Day Pricing
Here’s a detail most articles skip: many commission-driven products — traditional mutual funds and variable annuities — are priced only once per day, after the market closes. You don’t actually know the price you’re getting until after your order is already filled. Exchange-traded investments (stocks and ETFs), which make up the core of an independent, fee-only portfolio, trade in real time throughout the day on public exchanges — transparent, live pricing, so you always know exactly what you own and what it’s worth.
Transparent Fees You Can Actually See
With commission products, your true cost is often buried in expense ratios, sales loads, or surrender charges that you’d need a magnifying glass to find in the prospectus. Fee-only advisors charge a clear, disclosed fee—nothing hidden. Our fee schedule is disclosed upfront, before you become a client.
How This Adds Up to a More Secure Retirement
Put these pieces together — fiduciary duty, no quotas or sales pressure, open access to the full market instead of a limited product menu, collaborative decision-making, real-time pricing transparency, disclosed fees, and Schwab custody — and you get a retirement plan built with fewer conflicts of interest and more visibility at every step. That combination enables genuinely tax-efficient withdrawal planning, sensible risk management, and a strategy built around your goals rather than a sales target.
| Audit Factor | Fee-Only Fiduciary RIA | Commission / Brokerage Model |
|---|---|---|
| Standard of Care | Fiduciary Standard: Must legally put your best interests first at all times. | Suitability Standard: Products only need to be “suitable” when sold. |
| Compensation | Transparent flat rates, hourly structures, or steady AUM fees. | Variable sales loads, transactional commissions, and performance wraps. |
| Product Kickbacks | Strictly Prohibited: Cannot accept 12b-1 fees or revenue shares. | Allowed to collect ongoing trailing payouts from fund managers. |
| Primary Regulator | Registered directly with the SEC or state regulatory agencies. | Regulated by FINRA and state insurance compliance offices. |
Questions to Ask Any Overland Park Financial Advisor
Before you hire anyone, ask directly:
- Are you a fiduciary 100% of the time, or only in certain situations?
- Are you registered as an IAR? What’s your CRD number, so I can verify it?
- Are you fee-only, or do you also earn commissions?
- Who is the custodian of my funds?
- Can you recommend any product in the market, or only from an approved list?
If an advisor hesitates on any of these, that’s worth noting.
Talk to a Fee-Only Fiduciary in Overland Park
At Three Streams Financial, I work with individuals, families, and small business owners as an independent, fee-only Investment Adviser Representative — CRD #2131294 — with Charles Schwab as custodian and no proprietary products to sell. We proudly serve clients throughout the Kansas City metro area. If you’d like a second opinion on your current advisor relationship, or you’re starting from scratch, reach out or call (913) 274-9020.
Frequently Asked Questions
What is the main difference between a fee-only and a fee-based financial advisor?
A fee-only advisor is paid exclusively by fees from clients, with no commissions or product sales of any kind. A fee-based advisor combines client fees with commissions on certain products, like insurance or annuities, which can create conflicts of interest that a true fee-only model avoids entirely.
Is a fee-only fiduciary advisor more expensive than a commission-based advisor?
Not necessarily, and often the opposite once total costs are compared. Commission-based products frequently carry hidden costs — sales loads, surrender charges, and ongoing trailing commissions — buried in the prospectus. A fee-only advisor’s cost is a single, disclosed fee, which makes it easier to compare against the true, all-in cost of a commission product.
How do I verify that a financial advisor is actually fee-only and a fiduciary?
Search the advisor’s CRD number at the SEC’s Investment Adviser Public Disclosure website (adviserinfo.sec.gov), which shows their registration status, disciplinary history, and how they’re compensated. A legitimate fee-only fiduciary should provide this number without hesitation.
Why does it matter who custodies my investment accounts?
Your investments should be held by an independent, third-party custodian, such as Charles Schwab, rather than by the advisor or their firm directly. This separation protects your assets, since the custodian — not the advisor — physically holds and reports on your accounts, adding a layer of independent oversight.
Key Takeaways
- Fee-only advisors are paid exclusively by client fees and are held to a fiduciary standard; commission-based advisors are paid by product companies and held to a lower suitability standard.
- Independent, fee-only advisors can recommend any product across the market, not just a limited approved list from a broker-dealer.
- Assets should be held by an independent third-party custodian like Charles Schwab, not the advisor’s own firm.
- Any legitimate fee-only fiduciary should provide their CRD number for independent verification without hesitation.
To learn more:
- https://threestreamsfinancial.com/senior-tax-deductions-dividend-benefits-2025/
- https://threestreamsfinancial.com/diversify-investment-strategies-reduce-risk-safety/
- https://threestreamsfinancial.com/why-60-40-portfolio-fails/
Remember, there’s no one-size-fits-all approach to investing. Conduct thorough research, consider your personal circumstances, and consult a fee-only financial advisor before making any investment decisions.
Hello, I’m Dan Gould, an independent fee-only advisor based in Overland Park, KS. I offer comprehensive financial services to individuals, families, professionals, and small business owners nationwide. With over 25 years of experience in institutional financial markets, I deliver proven portfolio management and retirement income strategies.